Virtual Attendance - Bloomberg Quant (BBQ) October
Monday, October 19, 2026
5:30 PM - 7:00 PM Eastern Time
Please register to join us virtually for the October installment of the Bloomberg Quant (BBQ) Seminar Series – broadcast live from New York City. A link to the webcast will be emailed to you immediately upon registration.
In this seminar chaired by Bruno Dupire, Hélyette Geman will present the keynote, followed by “lightning talks” of 5 minutes each in quick succession.
5:30 PM
Keynote: Hélyette Geman | Research Professor in Mathematical Finance, Department of Applied Mathematics & Statistics, Johns Hopkins University
The Promise of Prediction Markets: From Bookmakers to Kenneth Arrow
The picturesque world of bookmakers writing on scratch paper wagers on sporting events placed over the phone has been challenged over the last few years by platforms such as Kalshi or Polymarket, where the volumes and contract types have been increasing in a staggering manner since the early 2020s. Remarkably, a 2008 paper by Ken Arrow and 19 prominent economists had argued in favor of these prediction markets (PMs) as a source of information.
Our goals for this talk are to look at regulatory issues around PMs, describe the most popular PM contracts and their possible valuation using founding results of quant finance, and lastly to question the relevance of the comparison of volatilities derived from financial markets and prediction markets.
6:30 PM
Lightning Talks
- Jan Vecer | Charles University in Prague
Portfolio Optimization through Information Theory - Valentin Tissot-Daguette | Bloomberg
Reproducing Kernel Hilbert Space (RKHS): An Inner View - Magaajyia Silberfeld | Songhay Empire Productions
Producing High Yields: When Talent Compounds - Arturo Cifuentes | CLAPES UC, Catholic University of Chile
A Goal-Driven Declining-CVaR Glidepath Approach for Target-Date Fund Design
Speakers
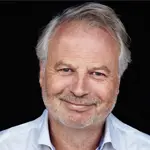
Bruno Dupire
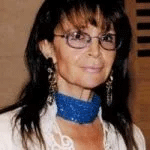
Hélyette Geman
Register
Only Roman/Latin (A-Z) letters, numbers, spaces, and the following special characters + - are accepted within this form.